The Legal Side of Hiring Remotely in 2026 (And How to Get It Right)
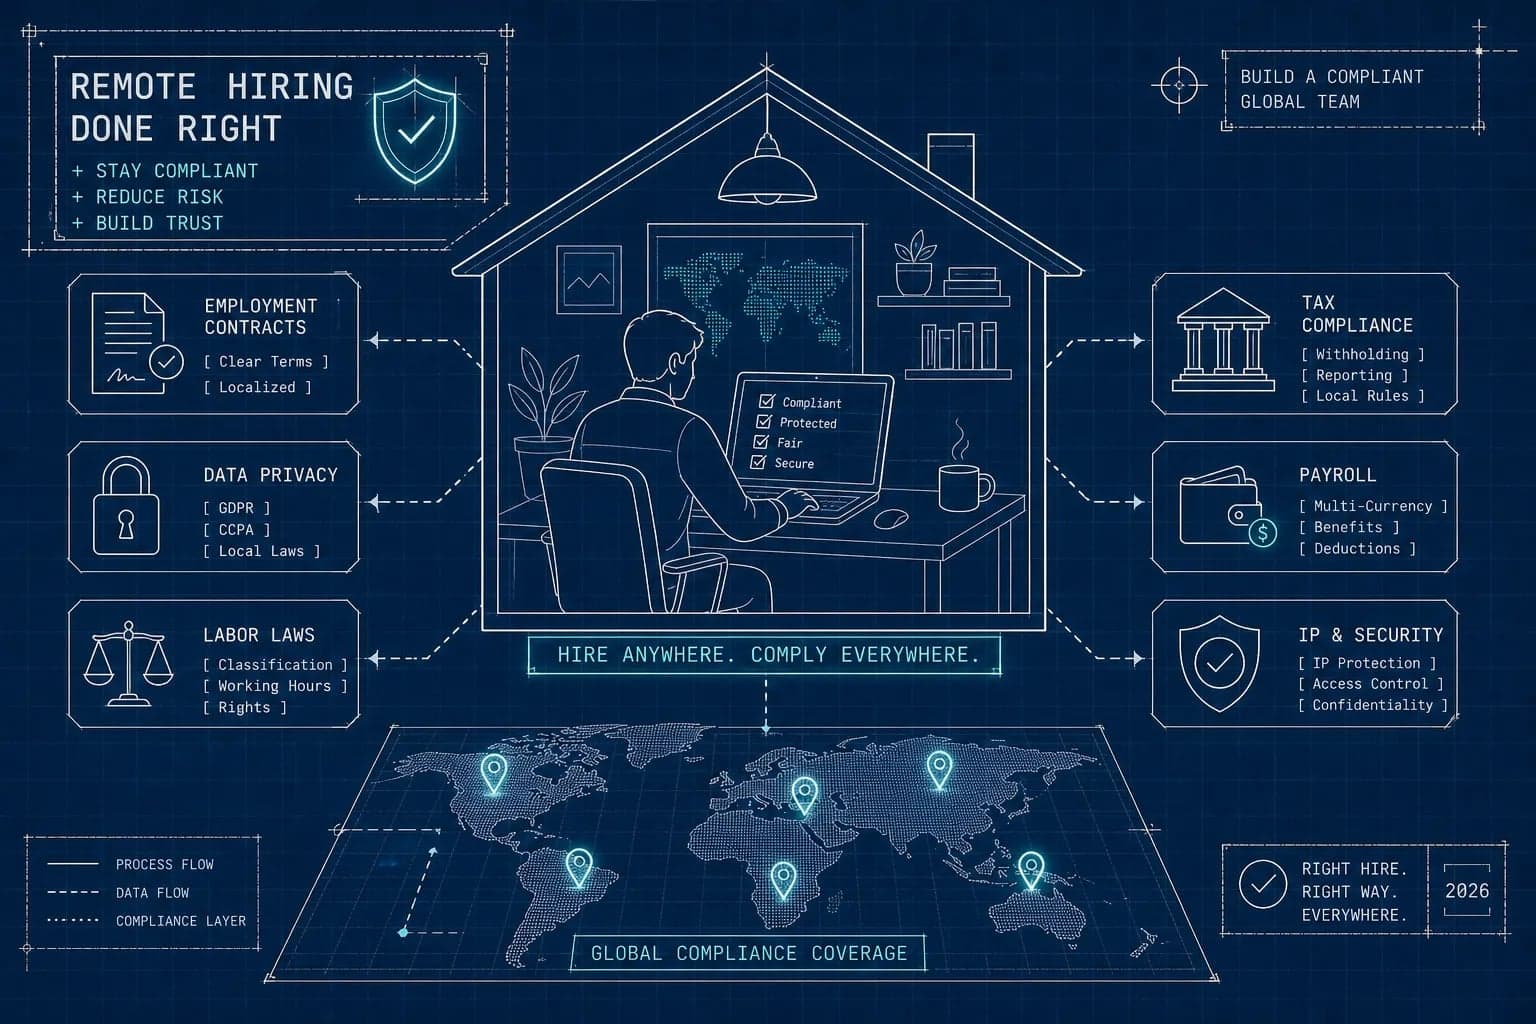
Before you contratar remotamente, that is, hire remotely across borders, you need to resolve four things: whether you can legally employ someone in their country without a registered entity, how their employment status is classified under local law, what payroll and tax registration is required, and how you handle right to work and data compliance. Much of the avoidable risk in cross-border remote hiring comes not from the hiring decision itself, but from skipping these steps. This guide walks through each one in plain language so you can move quickly without creating a compliance problem for later.
For UK companies expanding internationally, and for foreign businesses bringing on UK talent, solutions like AgileHRO’s Employer of Record model have made entityless hiring across 150+ countries a realistic option for startups and scale-ups that need to move fast. The four legal pillars below explain what you need to understand before any of that becomes relevant.
Key takeaways
- Entity risk comes first: Employing someone abroad without a local entity can create a taxable corporate presence. Assess this before advertising any role.
- Classification is decided by facts, not contracts: Calling someone a contractor does not make them one under local law. The actual working relationship is what authorities examine.
- IR35 adds a UK-specific layer: Medium and large businesses engaging personal service companies must assess status, issue a Status Determination Statement, and operate PAYE where appropriate.
- Payroll obligations follow the worker: Employment income is generally taxed where the work is performed, subject to applicable tax treaties and residence rules.
- Right to work obligations apply to remote roles: Working from home does not remove the requirement to complete a compliant check before employment begins.
- GDPR applies across borders: Transferring employee data internationally requires a lawful transfer mechanism, not just a well-intentioned privacy policy.
Do you need a legal entity in every country where you contratar remotamente?
Most companies assume they need a local subsidiary before they can employ someone abroad. That assumption slows the remote hiring process significantly and adds cost that is often unnecessary. The real question is whether the specific arrangement you are planning creates a compliance obligation, and there are three legally distinct routes available.
What “permanent establishment” risk means for remote employers
Employing someone abroad can create a taxable corporate presence, known as a permanent establishment (PE), even without a registered office. This happens when an employee habitually concludes contracts, plays the principal role in securing contracts that the business routinely accepts, or performs core commercial functions from a fixed location such as a home office. A UK company whose remote employee negotiates deals or manages local operations from another country may find itself liable for local corporate tax, back-reporting, and registration requirements it never anticipated.
This PE risk is separate from employment law compliance: both need to be assessed before you recruit any distributed team member. The threshold varies by country and by the applicable UK tax treaty, and the consequences of getting it wrong include local corporate tax on attributable profits, transfer-pricing obligations, and potential VAT and payroll liabilities. Short-term, employee-requested remote work involving routine internal duties typically carries lower risk; permanent arrangements involving sales, contract, or management functions carry substantially higher exposure.
The three routes: local entity, Employer of Record, or genuine contracting
An Employer of Record employs the worker on your behalf in-country, handling local contracts, payroll, and statutory benefits without requiring you to set up a subsidiary. Genuine contracting is an option only when the working relationship genuinely qualifies: the contract label alone does not decide this, and a worker described as a contractor can still be treated as an employee under local law. Once you have assessed the risk, the choice of engagement structure becomes clearer. Each route has a different profile on cost, speed, and compliance responsibility.
| Route | Setup time | Cost | Legal responsibility | Payroll compliance | Flexibility |
|---|---|---|---|---|---|
| Local entity | Weeks to months | High (registration, accountants, ongoing admin) | Hiring company | Managed in-house or by local provider | Low (permanent structure) |
| Employer of Record (EOR) | Often days (provider and country dependent) | Per-employee fee (variable by provider and country) | EOR provider is legal employer | Managed by EOR | High (scalable, no long-term commitment) |
| Independent contractor | Immediate | Variable (invoiced) | Shared, depends on classification | Not applicable if genuinely self-employed | High, but classification risk applies |
Employee or contractor: why this decision carries more legal weight than you might expect
Worker classification is the most commonly mishandled part of the remote hiring process for cross-border teams. The written contract is one input, but it is not the deciding factor. Authorities examine the actual working relationship: who controls how work is performed, whether the individual must provide the service personally, whether there is mutuality of obligation, how integrated the worker is into the business, who bears financial risk, and whether the person is free to work for others simultaneously.
A worker described as a contractor in a written agreement can still be treated as an employee under local law, creating backdated tax, social-security, holiday pay, and pension liabilities. The risk compounds when you have workers misclassified across multiple jurisdictions at the same time. Periodic review matters here: a contractor engagement that becomes exclusive, continuous, or closely managed over time is increasingly likely to be reclassified, regardless of how the original contract was structured.
IR35 and its international equivalents
For UK engagements involving personal service companies, the off-payroll working rules require medium and large private-sector businesses to assess employment status, issue a Status Determination Statement, and operate PAYE where the engagement is inside IR35. The practical effect is that the tax and National Insurance treatment that would apply to a direct employee must apply to the deemed employment payment.
Many other countries have their own equivalent tests. Germany’s Scheinselbstständigkeit rules focus on genuine independence; France, Spain, and Brazil each apply distinct employment and social-security frameworks. A relationship structured to be compliant in the UK may still trigger employee status in the worker’s home country, so each jurisdiction needs its own assessment rather than a one-size-fits-all assumption.
What payroll and tax compliance requires when your team spans borders
Employment income is generally taxed where the work is physically performed, not where the employer is headquartered, though tax treaties, residence rules, short-term visit exemptions, and bilateral social-security agreements can change the outcome in specific cases. That principle drives most of the compliance obligations for remote teams, and it applies whether your business is UK-based hiring abroad or an overseas company bringing on UK talent.
UK PAYE, National Insurance, and employer obligations
UK employees require PAYE registration, income tax and National Insurance deductions, employer NI contributions, auto-enrolment pension, and statutory holiday and sick pay. HMRC requires Real Time Information (RTI) reporting on or before each payday, with penalties for late filing. For foreign companies hiring UK-based remote employees, these obligations may apply depending on the level of UK presence the overseas employer has, and an overseas employer may choose to operate PAYE voluntarily even where no formal UK presence exists. Seek advice from HMRC or a qualified adviser on your specific circumstances.
AgileHRO’s UK EOR service is designed for exactly this scenario: running compliant UK payroll on behalf of overseas businesses without them needing to register a UK entity or manage PAYE in-house.
Withholding tax, social security, and mandatory benefits abroad
For employees based outside the UK, you typically need to register as a local employer, withhold local income tax, pay employer and employee social-security contributions, provide statutory leave and benefits, and file periodic payroll reports. Tax treaties, residence rules, and short-stay exemptions can change the outcome in specific cases, but each country needs a separate assessment. Managing multi-currency payroll across several jurisdictions on spreadsheets is where the operational burden of remote contractor hiring and employee payroll becomes unsustainable, and where a global payroll platform becomes genuinely useful.
What do right to work checks and GDPR require when you contratar remotamente?
Two compliance requirements trip up remote employers more than almost any other: the right to work obligation and UK GDPR’s rules on processing and transferring employee data internationally. Both are non-negotiable regardless of whether the role is office-based or fully remote.
Right to work: does working from home change the obligation?
UK employers must complete a compliant right to work check before employment begins, whether the role is office-based, hybrid, or fully remote. Working from home does not remove this obligation. Checks are completed through original documents or the Home Office online share-code process; the process for EU nationals post-Brexit differs from pre-2021 rules and must be followed correctly. For employees working entirely outside the UK, the relevant country’s immigration rules apply instead, but you must still verify that the worker’s immigration status in their country permits the type of work being performed.
UK GDPR and cross-border employee data
UK employers handling worker data must comply with the UK GDPR and the Data Protection Act 2018: establish a lawful basis for processing, provide a clear employee privacy notice, limit data collection, and apply appropriate security and retention controls. Transfers of employee data from the UK to other countries require an adequacy decision, approved contractual safeguards, or another lawful transfer mechanism, in line with ICO guidance on international transfers. When a distributed team spans multiple countries, the EU GDPR and local privacy laws may apply simultaneously alongside the UK regime.
Monitoring remote employees through screen capture, activity tracking, or keylogging carries specific proportionality requirements. In line with ICO guidance on workplace monitoring, a Data Protection Impact Assessment should be completed before deploying any monitoring tools, and employees must be informed transparently about what is collected and why.
The compliance checklist to complete before your first cross-border hire
The four pillars above are interconnected: skipping one creates risk in the others. The sequence below gives you a practical framework to work through before making any cross-border offer when you contratar remotamente.
- Confirm the worker’s physical work location and any planned travel.
- Assess employment status under both UK and local law.
- Check immigration and right-to-work requirements in the relevant country.
- Assess payroll registration, withholding, social-security, pension, and corporate-tax exposure.
- Choose the engagement route: direct employment with a local entity, Employer of Record, or genuine contractor arrangement.
- Prepare a locally compliant employment agreement or contractor agreement with a statement of work.
- Put payroll, benefits, data-transfer, and record-keeping processes in place before day one.
Step five is often where the decision becomes clear. Companies that cannot, or do not want to, open a local entity need a compliant alternative. AgileHRO acts as the legal employer in-country, handling local contracts, payroll, tax, and statutory benefits across 150+ countries, so your team retains day-to-day direction of the work without taking on the compliance burden of a foreign entity. The Employment Cost Calculator on the AgileHRO platform shows the full cost of hiring in any country versus setting up a local entity, without a sales call, so your finance team can make a properly informed decision before committing.
Hiring remotely across borders is manageable when you follow the right sequence
Entity route, classification, payroll compliance, and right to work plus GDPR are not isolated checkboxes. They are a connected framework, and the biggest mistakes in cross-border remote hiring almost always come from treating them separately or assuming that a well-worded contract resolves everything. It does not. The actual working relationship, the physical location of the worker, and the obligations that flow from both are what determine your exposure, whether you contratar remotamente into a single new market or across a dozen.
The compliance process is learnable and repeatable once you have done it properly the first time. The seven-step checklist above gives you the sequence. For companies working through remote employee onboarding across borders for the first time, AgileHRO’s Employment Cost Calculator and interactive platform tour are a no-pressure place to start. Run the numbers on your target country, see what the engagement would look like in practice, and get in touch with our team to work through the specifics with a dedicated specialist.
Frequently Asked Questions
Can an overseas employer choose to operate UK PAYE even without a UK entity?
Yes, we note that an overseas employer may choose to operate UK PAYE voluntarily even where no formal UK presence exists. Whether to do so should be assessed with HMRC or a qualified adviser because obligations like PAYE, National Insurance and Real Time Information reporting can apply depending on the level of UK presence.
How does permanent establishment (PE) risk change depending on the role the remote worker performs?
We state that PE risk is lower for short-term, routine internal duties and substantially higher for permanent arrangements involving sales, contract conclusion or management functions. The specific threshold varies by country and by applicable tax treaty, so roles that habitually conclude contracts or perform core commercial functions from a fixed location carry greater exposure.
Can a foreign employer operate UK PAYE voluntarily for UK-based remote employees?
We note that an overseas employer may choose to operate PAYE voluntarily even where no formal UK presence exists. Whether UK PAYE, National Insurance and auto-enrolment obligations apply depends on the level of UK presence the overseas employer has, and advice from HMRC or a qualified adviser is recommended for specific cases.
What international transfer mechanisms satisfy UK GDPR when sending employee data abroad?
We explain that transfers from the UK require an adequacy decision, approved contractual safeguards, or another lawful transfer mechanism in line with ICO guidance. Employers must also establish a lawful basis for processing, provide a clear employee privacy notice, limit data collection and apply appropriate security and retention controls.
When do the UK IR35 rules apply to engagements with personal service companies?
We point out that medium and large private-sector businesses engaging personal service companies must assess status, issue a Status Determination Statement and operate PAYE where the engagement is deemed inside IR35. The practical effect is that the tax and National Insurance treatment that would apply to a direct employee must be applied to the deemed employment payment.